Imagine checking your brokerage account on a random Tuesday morning and finding a cash deposit sitting there money that showed up without you selling a single share, timing the market, or doing anything at all except waiting. That's not a fantasy. It's what happens every quarter for millions of investors who've built a dividend growth portfolio. You didn't work for that money this week. You worked for it years ago, when you bought the shares and let compounding do the rest.
That's the entire appeal of dividend growth investing in one sentence: get paid to own good businesses, and get paid more every year, whether the market is up, down, or sideways.
But here's the catch nobody tells beginners in 2026 the strategy doesn't look the way it did ten years ago. The S&P 500's overall dividend yield has quietly drifted lower, not because companies stopped paying, but because the index itself has changed shape. If you build your income portfolio the way your parents did, using a plain index fund and calling it a day, you're going to be disappointed by the paycheck.
This guide walks through exactly what's changed, why it matters, and how to build a dividend growth portfolio that actually works in today's market.
Quick Summary 5 Things to Know
Dividend growth investing means buying companies with a track record of raising dividends not just the highest yield you can find today.
The S&P 500's average yield (~1.05%–1.1% in mid-2026) is unusually low because mega-cap tech stocks now dominate the index not because dividends are shrinking.
The S&P 500 Dividend Aristocrats companies with 25+ years of consecutive increases currently yield closer to 2.5%–2.8%.
Reinvested dividends are still taxable in the year they're paid, even inside a DRIP, unless held in a tax-advantaged account.
A durable dividend growth portfolio is built on quality screening, sector diversification, and automatic reinvestment reviewed annually, not daily.
Table of Contents
What Is Dividend Growth Investing?
Why Dividend Yields Look Different in 2026
How Dividend Growth Investing Actually Works
Building a Dividend Growth Portfolio: Step by Step
Real-World Example: A $50,000 Starter Portfolio
Dividend Aristocrats and Dividend Kings Explained
Dividend Stocks vs. Dividend ETFs
How Dividends Are Taxed
Pros and Cons of Dividend Growth Investing
Common Mistakes Investors Make
Expert Tips for Long-Term Success
Frequently Asked Questions
Key Takeaways
Sources & References
What Is Dividend Growth Investing?
Dividend growth investing is a strategy built around one simple filter: don't just buy stocks that pay dividends buy stocks with a track record of raising those dividends, year after year, through good markets and bad ones.
It sounds like a small distinction. It isn't.
A company yielding 6% today with a stagnant or shrinking dividend is a completely different animal than a company yielding 2% today that raises its payout by 8–10% annually. The first one might be a value trap a business the market has already priced for trouble. The second one is quietly compounding your income stream every single year, regardless of what its stock price does in the short term.
What Separates a Dividend Growth Company From an Ordinary Dividend Payer
A durable, often recession-resistant business model
Free cash flow that comfortably covers the dividend (a healthy payout ratio)
A multi-year ideally multi-decade streak of consecutive increases
A management team and board culture that treats the dividend as a promise to shareholders, not a discretionary line item
Did You Know? S&P Dow Jones Indices has been tracking companies with long dividend-growth histories since the early 1970s. To officially qualify for the S&P 500 Dividend Aristocrats index today, a company must be a current S&P 500 member and must have raised its dividend every year for at least 25 consecutive years, with a minimum float-adjusted market cap of $3 billion.
Why Dividend Yields Look Different in 2026
If you've pulled up a chart comparing today's S&P 500 dividend yield to its long-run historical average, you've probably done a double take. As of mid-2026, the index's aggregate dividend yield sits at roughly 1.05%–1.08%, meaningfully below its long-term historical average of approximately 1.6%.
Your first instinct might be to assume corporate America has gotten stingier with cash. It hasn't. What changed is the composition of the index itself.
A small handful of massive technology companies often nicknamed the "Magnificent Seven" now represent an outsized share of the S&P 500's total market capitalization. Most of them pay little to no dividend at all, preferring to reinvest cash into growth, buybacks, or simply hold it. Because the index is weighted by market cap, these low-yield (or zero-yield) giants pull the average yield down mathematically, even while dividend-focused indexes elsewhere in the market keep growing their payouts. The S&P 500 Dividend Aristocrats index, for comparison, has recently yielded closer to 2.5%–2.8% well above the broad index average.
Key Statistics Mid-2026
Index / Sector
Approximate Yield
Dividend Growth Trend
S&P 500 (broad index)
~1.05%–1.1%
Diluted by mega-cap tech
S&P 500 Dividend Aristocrats
~2.5%–2.8%
25+ year increase streaks required
Nasdaq-100 (growth-heavy)
~0.6%
Prioritizes growth over income
Traditional dividend sectors (utilities, staples, REITs)
3%–7%+
Often outpaces inflation
Table data compiled from S&P Dow Jones Indices and GuruFocus market data as of mid-2026; yields fluctuate daily with market prices and should be independently verified before making investment decisions.
The practical takeaway: a plain S&P 500 index fund is a fine core holding for growth, but it will not, on its own, build you a meaningful income stream in today's market. If dividend income is your goal, you have to go find it deliberately in specific sectors, specific companies, or dividend-focused funds that intentionally screen for consistent payers rather than tracking the broad, tech-heavy index.
How Dividend Growth Investing Actually Works
Strip away the jargon, and dividend growth investing runs on three interlocking engines.
1. Starting Yield What You Locked In, Not What's Advertised Today
Your real yield relies on your original purchase price, not the current share price. Buy a stock at $50 with a $1.50 annual dividend, and you've locked in a 3% yield on your cost basis permanently, regardless of where the stock trades afterward.
2. Dividend Growth Rate Your Automatic Raise
A company that grows its dividend 6–10% annually is effectively giving you a raise every year without you lifting a finger.
3. Reinvestment The Compounding Accelerant
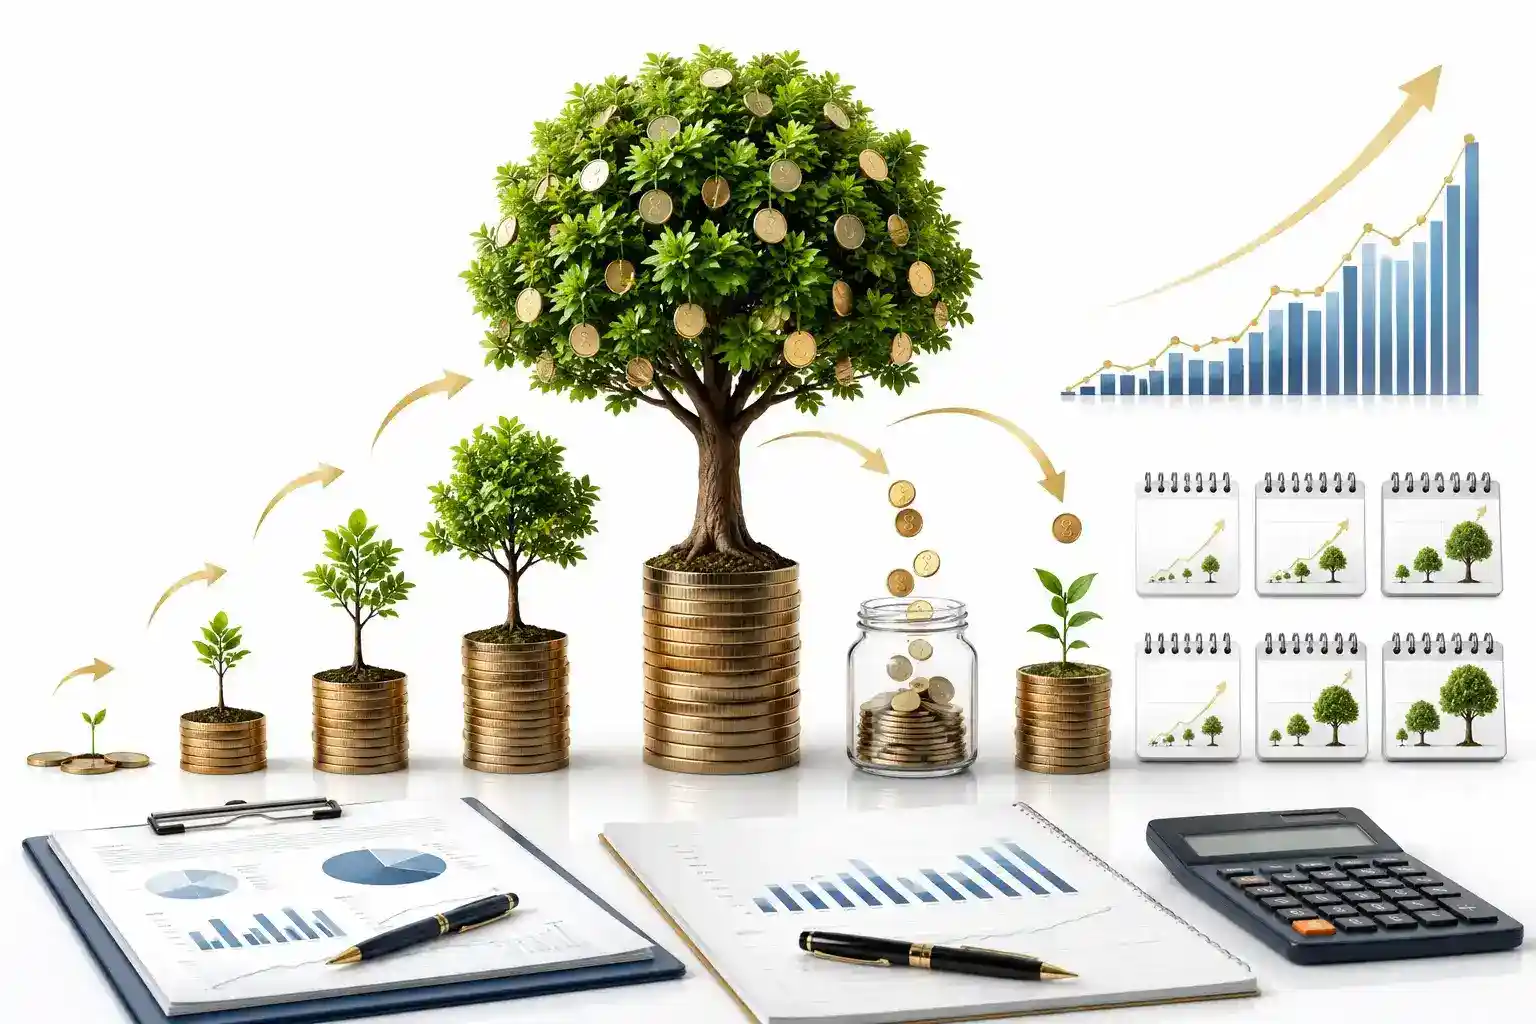
Reinvesting dividends using each payout to automatically buy more shares means your next dividend payment is calculated on a larger share base. This is the mechanism behind a Dividend Reinvestment Plan, or DRIP. As Charles Schwab's investor education team explains, a DRIP automatically reinvests dividends and capital gains distributions to purchase additional shares of the same security, typically at no charge, creating a compounding effect over years or decades. The SEC's Investor.gov similarly notes that DRIPs let investors buy more shares of a stock they already own by reinvesting dividend payments back into the company.
[Image: Dividend Growth Compounding Illustration]
Worked example: Say you invest $10,000 in a fund with a 2.5% starting yield and a 7% average annual dividend growth rate, reinvesting every payment along the way. Assuming share price appreciation roughly tracks earnings growth over time, your annual income from that original $10,000 could realistically grow several-fold over 20 years without ever adding another dollar of new capital. That's the entire bet dividend growth investors are making: not on next quarter's stock price, but on time, discipline, and compounding doing the heavy lifting.
Want to estimate your future passive income? Try our free Dividend Growth Calculator.
Building a Dividend Growth Portfolio: Step by Step
Step 1: Define Your Actual Goal
Are you building supplemental income you'll spend soon, or a retirement income stream you won't touch for 20–30 years? This single decision changes how much you weight current yield versus growth rate.
Step 2: Choose Your Vehicle
Approach | Best For | Trade-off |
|---|---|---|
Individual dividend stocks | Investors who enjoy research and want concentrated conviction bets | More time-intensive, higher single-stock risk |
Dividend-focused ETFs | Investors who want instant diversification with low effort | Less control, small management fees |
Blended approach | Most long-term investors | Core ETF holding plus select individual names |
Step 3: Screen for Quality, Not Just Yield
The single most common beginner trap in this strategy is picking stocks off a screener sorted by "highest yield." Resist it. An unusually generous yield relative to a sector's average is frequently the market pricing in an expected dividend cut not a bargain waiting to be found.
A better screening checklist:
✅ Payout ratio generally under 60–70% of earnings (REITs and utilities typically run higher due to their business structure)
✅ At least 5–10 consecutive years of dividend increases, minimum
✅ Consistent or growing free cash flow, not just accounting earnings
✅ Debt levels manageable relative to industry peers
✅ A business model you could explain to a friend in one sentence
Step 4: Diversify Across Sectors, Not Just Companies
Owning 15 dividend stocks means very little if 12 of them are utilities. A well-built dividend portfolio typically spans healthcare, consumer staples, industrials, financials, utilities, and real estate.
Step 5: Automate Reinvestment
Most major brokerages including Fidelity and Charles Schwab offer commission-free dividend reinvestment into fractional shares. Fidelity's fractional share program, for example, automatically reinvests fractional dividends in the same manner as full shares for enrolled accounts. Turning this on removes the temptation to spend the cash and keeps compounding running quietly in the background.
Step 6: Review Annually, Not Daily
Dividend growth investing rewards patience. An annual review checking payout ratios, growth rates, and flagging any dividend cuts or freezes is generally sufficient for a well-constructed portfolio.
Real-World Example: A $50,000 Starter Portfolio
Here's a simplified illustration of how a diversified dividend growth portfolio might be structured. This is for educational purposes only not a personalized recommendation.
[Image: Portfolio Allocation Infographic]
Allocation | % of Portfolio | Purpose |
|---|---|---|
Broad dividend growth ETF | 40% | Core diversification |
Consumer staples & healthcare stocks | 20% | Defensive, stable payers |
Utilities & REITs | 20% | Higher current yield |
Financials & industrials | 15% | Cyclical growth potential |
Cash reserve | 5% | Flexibility for opportunities |
Dividend Aristocrats and Dividend Kings Explained
Two terms show up constantly once you start researching this strategy.
Dividend Aristocrats are S&P 500 member companies that have increased their dividend every year for at least 25 consecutive years. This is an official, published index maintained by S&P Dow Jones Indices not just an informal nickname. To qualify, a company must currently be an S&P 500 constituent, have a float-adjusted market cap of at least $3 billion, and meet minimum trading-liquidity requirements.
Dividend Kings is the informal industry term for companies with 50 or more consecutive years of dividend increases. S&P Dow Jones Indices maintains an official equivalent the S&P Dividend Monarchs® Index which requires 50+ consecutive years of increases and targets a minimum of 25 constituents. A streak that long means the company kept raising its dividend through the dot-com crash, the 2008 financial crisis, and the 2020 pandemic without a single cut.
These lists are an excellent starting point for research, but membership alone isn't a guarantee of future performance. A company can technically remain an Aristocrat while showing warning signs a stretched payout ratio, slowing growth, rising debt that suggest the streak might not last forever. Always pair the streak with a look at current fundamentals, not just the historical record.
Dividend Stocks vs. Dividend ETFs: Dividend Growth Investing in 2026
Factor | Individual Dividend Stocks | Dividend ETFs |
|---|---|---|
Diversification | Low unless you own many names | Instant, built-in |
Research required | High ongoing monitoring per company | Low fund methodology does the screening |
Control | Full control over exact holdings | Limited to fund methodology |
Cost | No management fee, but trading/research time | Small expense ratio (often 0.05%–0.35%) |
Single-company risk | Real a cut can hurt disproportionately | Diluted across dozens or hundreds of holdings |
Most experienced dividend investors eventually land on a blend: an ETF as the diversified core, with a handful of individual stocks layered on top for names they have high conviction in.
How Dividends Are Taxed
This is one of the most misunderstood parts of the strategy, and it's worth getting right before you build a large taxable position.
The IRS classifies dividends as either ordinary or qualified. Ordinary dividends are taxed at your regular federal income tax rate, which tops out at 37%. Qualified dividends which must generally be paid by a U.S. corporation or a qualifying foreign company, and held for a minimum period around the ex-dividend date are instead taxed at the lower long-term capital gains rates of 0%, 15%, or 20%, depending on your taxable income. High earners may also owe an additional 3.8% Net Investment Income Tax on top of either rate.
Critical Point: Reinvesting dividends through a DRIP does not make them tax-free. The IRS and every major brokerage confirm that dividends are taxable in the year received, whether you take the cash or automatically reinvest it. This is a common point of confusion for new dividend investors, so it's worth repeating: your 1099-DIV will show the dividend income regardless of what you did with the cash.
Holding dividend-paying investments inside a tax-advantaged account, such as an IRA or 401(k), can defer or eliminate this annual tax drag but the specific rules depend on the account type. A tax professional can confirm what applies to your situation.
Pros and Cons of Dividend Growth Investing
Pros
Generates a growing income stream that can outpace inflation over time
Tends to favor financially disciplined, well-managed companies
Historically exhibits less volatility than high-growth stock portfolios
Reinvested dividends significantly accelerate long-term compounding
Offers psychological comfort during downturns cash still arrives even when prices fall
Cons
Lower current yields than some higher-risk income alternatives
Dividend cuts can still happen, even at well-established companies, during severe downturns
Overweighting dividend payers can mean underexposure to high-growth sectors like technology
Requires genuine patience meaningful compounding takes a decade or more, not months
Dividend income is generally taxable every year, even when reinvested, unless held in a tax-advantaged account
Common Mistakes Investors Make
Chasing yield without checking sustainability. A stock yielding 9% when its sector averages 3% is usually signaling trouble, not offering a bargain.
Ignoring the payout ratio. A company distributing more than it earns cannot sustain that dividend indefinitely.
Lack of diversification. Loading up on a single sector, commonly energy or REITs, adds unnecessary concentration risk.
Spending dividends too early. Skipping reinvestment during your accumulation years dramatically slows the compounding effect.
Panic-selling after a single dividend cut. One cut doesn't automatically mean a broken business the underlying cash flow trend matters more than the headline.
Overlooking taxes. Assuming reinvested dividends are somehow tax-deferred is a common and costly misunderstanding.
Expert Tips for Long-Term Success
Prioritize the dividend growth rate over the starting yield if your time horizon is 15+ years.
Blend ETFs and individual stocks to combine broad diversification with high-conviction picks.
Track "dividend growth streaks" as a screening tool, not just current yield.
Rebalance annually on a schedule, not reactively after every earnings report.
Hold dividend-paying positions in tax-advantaged accounts where possible to reduce the annual tax drag on reinvested income.
Frequently Asked Questions About Dividend Growth Investing in 2026
Is dividend growth investing better than growth investing? Neither is objectively "better" they serve different goals. Growth investing targets capital appreciation with little or no income, while dividend growth investing targets a rising income stream with typically lower volatility. Many long-term investors blend both.
How much money do I need to start? There's no real minimum. Major brokerages including Fidelity and Charles Schwab allow fractional share purchases Schwab's Stock Slices program allows purchases starting at $5, and Fidelity's Stocks by the Slice starts at $1 so you can begin building a dividend growth portfolio with a very small amount of capital.
Are dividend ETFs safer than individual dividend stocks? ETFs offer instant diversification, which reduces single-company risk, but they aren't immune to broad market declines or sector-wide dividend cuts affecting many holdings at once.
Do I have to pay taxes on reinvested dividends? Yes, generally. In most taxable brokerage accounts, dividends are taxable in the year they're paid, even when automatically reinvested through a DRIP. Tax-advantaged retirement accounts often work differently confirm the rules for your account type with a tax professional.
What's a "safe" payout ratio? There's no universal number, but a payout ratio under roughly 60–70% of earnings is often considered sustainable for most industries, with higher thresholds typical for REITs and utilities given their structurally different business models.
Key Takeaways: Dividend Growth Investing in 2026
Dividend growth investing prioritizes companies with a track record of raising dividends, not just paying the highest yield available today.
The S&P 500's overall yield sits near 1.05%–1.1% in 2026, well below its ~1.6% long-term average, largely because low-yield mega-cap tech now dominates the index.
The S&P 500 Dividend Aristocrats index requires 25+ consecutive years of dividend increases and currently yields closer to 2.5%–2.8%.
Reinvested dividends are still taxable in the year received a DRIP does not defer taxes in a standard brokerage account.
Diversify across sectors, automate reinvestment, and review your portfolio annually rather than reactively.
This article is for educational purposes only and does not constitute personalized financial or tax advice. Consult a licensed financial advisor or tax professional before making investment decisions. Yields, index compositions, and tax figures cited above reflect data available as of mid-2026 and face change; verify current figures before acting on them.
About the Author
Admin Founder, FinanceFlows
Admin is the founder of FinanceFlows, where he writes educational articles about investing, ETFs, dividend investing, passive income, and personal finance. His work draws on trusted public sources, including the SEC, IRS, S&P Dow Jones Indices, Nasdaq, Fidelity, Charles Schwab, and Investor.gov, to help readers make sense of the fundamentals before making their own financial decisions.
Related Guide: Read our complete breakdown on SpaceX Stock Crashes 14% Despite Earnings Beat as $101 Billion Share Lockup Hits the Market.
Related Guide: Read our complete breakdown on Nvidia's $500 Billion AI Financing Deal Explained: What the Goldman Sachs and Apollo Partnership Means.
Related Guide: Read our complete breakdown on Nvidia's Secret $21 Billion SpaceX Stake: How a Chip Deal Became a Rocket Fortune.
Related Guide: Read our complete breakdown on Health Care and Biotech Stocks Hit Record Highs in 2026 as Investors Flee Pricey Tech.
Related Guide: Read our complete breakdown on Nvidia Reportedly Agrees to Buy Hugging Face for $12.9 Billion: Why This Would Be Its Biggest Deal Ever.
Related Guide: Read our complete breakdown on How Compound Interest Works: The Math Behind Wealth.
Sources & Authoritative Citations
S&P Dow Jones Indices S&P 500 Dividend Aristocrats
Charles Schwab How a Dividend Reinvestment Plan Works
U.S. Securities and Exchange Commission, Investor.gov Direct Investing / Dividend Reinvestment Plans
S&P Dow Jones Indices S&P 500 Dividend Aristocrats Index Methodology (eligibility criteria: S&P 500 membership, 25-year increase streak, $3B minimum float-adjusted market cap)
S&P Dow Jones Indices S&P Dividend Monarchs® Index Methodology (50+ year dividend increase requirement)
Internal Revenue Service Topic no. 404, Dividends and Other Corporate Distributions
Fidelity What Are Qualified Dividends and How Are They Taxed?
Related Financial Guides & Tools
📊 Related Tool: Instead of guessing what an annual 7% dividend increase will yield in year ten, simulate your future yield on cost with our dividend income and DRIP calculator. If your ultimate goal is to retire early on passive dividend streams without selling equity shares, calculate your target nest egg on our FIRE calculator.
🧮 Build Your Dividend Income Projection
Input your starting portfolio, yield, monthly contributions, and dividend growth rate to see your year-by-year passive income and the compounding impact of DRIP over 10–30 years.
Use the Dividend DRIP Calculator →Frequently Asked Questions: Dividend growth investing
What is dividend growth investing and why does it matter?
Dividend growth investing provides crucial financial direction for investors and households. Understanding dividend growth investing helps you make informed allocation choices, reduce unnecessary fees, and optimize your overall returns.
How can you apply dividend growth investing in your financial strategy?
To implement dividend growth investing successfully, start by assessing your current risk profile and timeline. Consistently monitoring dividend growth investing ensures your portfolio stays aligned with long-term goals.
What are common pitfalls to avoid with dividend growth investing?
The most common mistake when evaluating dividend growth investing is reacting to short-term market noise. Focus on verifiable data, compound growth, and proven principles when making decisions based on dividend growth investing.